No currency boards have failed. Furthermore, the results from currency boards have always been positive. Economies with currency boards have consistently had lower inflation, lower interest rates, smaller budget deficits, and higher GDP growth than their peers.
Contemporary Empirical Results
1. Inflation Collapses
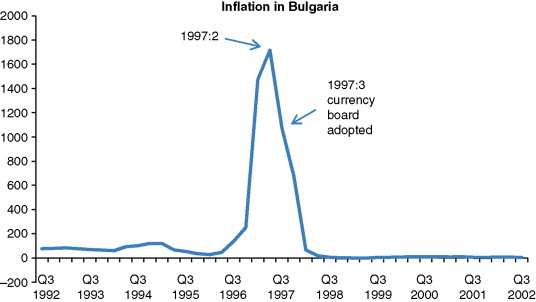
Currency boards have a perfect track record of crushing inflation when introduced after periods of monetary instability.
- Hong Kong (1983): Inflation dropped from 11% in 1982 to 3.5 % in 1985.
- Estonia (1992): Annual inflation fell from 1,053% in 1992 to 35.6% in 1993.
- Lithuania (1994): Annual inflation fell from 410.7% in 1993 to 24.6% in 1996.
- Bulgaria (1997): Annual inflation fell from 549.2% in 1997 to 1.6% in 1998.
- Bosnia (1997): Annual inflation fell from 95.6% in 1996 to -0.40% in 1998.
2. Interest Rates Come Down
As a result of declining inflation, interest rates decline, too.
- Hong Kong (1983): Inflation dropped from 11% in 1982 to 3.5 % in 1985.
- Estonia (1992): Annual inflation fell from 1,053% in 1992 to 35.6% in 1993.
- Lithuania (1994): Annual inflation fell from 410.7% in 1993 to 24.6% in 1996.
- Bulgaria (1997): The money market rate fell from 117.66% per annum in 1996 to 2.43% per annum in 1998.
- Bosnia (1997): Annual inflation fell from 95.6% in 1996 to -0.40% in 1998.
3. Fiscal Authorities Face A Hard Budget Constraint
Currency boards cannot extend credit to the fiscal authorities therefore, a hard budget constraint in imposed.
- Bulgaria (1997): The fiscal balance went from -8.1 % of GDP in 1996 to 1.1% of GDP in 1998.
4. Deposit Inflows To The Banking System Increase
Arbitrage between the newly issued currency board, domestic money, and the anchor stimulate deposit inflows into the banking system.
- Bulgaria (1997): Schuler Data
5. Capital Inflows To The Currency Board Country Increase
An exchange rate in which the domestic currency is freely convertible and trades at a fixed exchange rate with its anchor currency eliminates exchange rate risk and facilitates both portfolio and foreign direct investment inflows.
- Bulgaria (1997): Foreign Reserves (millions of U.S. dollars) increased from 864 in 1996 to 3,056 in 1998.
6. Economic Growth Accelerates
The installation of a currency board results in a positive confidence shock, and the establishment of stability.
- Bulgaria: Change in Real GDP went from -14.2% in 1997 to 4.3% in 1998
- Estonia:
- Lithuania:
“Stability is not everything, but without stability, everything is nothing.” - Dr. Karl Schiller, West Germany’s Economics Minister between 1966 and 1972
Why Currency Boards Outperform Central Banks
My argument is straightforward: rules beat discretion.
Feature | Currency Board | Central Bank |
Monetary discretion | None | High |
Reserve backing | 100% | Variable |
Inflation outcomes | Consistently low | Mixed |
Credibility | High | Dependent on policymakers |
Political interference | Impossible | Common |
Read up on my work in 🇧🇬 Bulgaria, 🇪🇪 Estonia, and 🇱🇹 Lithuania, three countries where currency boards turned chaos into stability.
The Historical Record: 175 Years of Currency Boards
The Data: Prof. Hanke and Kurt Schuler analyzed financial data for all 70 currency boards established since the first one — the Mauritius Currency Board in 1849 — through the late twentieth century. The findings are comprehensive and unambiguous.
Key Statistics
- First currency board: Mauritius, 1849
- Total currency boards established: 70
- Successful speculative attacks: 0 (zero)
- Cases of real exchange rate appreciation causing competitiveness loss: 0 (zero)
- Hyperinflations under properly functioning currency boards: 0 (zero)
- Countries with currency boards that had higher inflation than comparable central bank countries: 0 (zero)
Currency Board Successes: Modern Case Studies
Country | Year Established | Anchor Currency | Key Achievement |
Mauritius | 1849 | Sterling | First currency board in history; pioneered the institutional design used by all subsequent boards |
Hong Kong | 1983 | USD | 40+ years of monetary stability; survived Asian crisis, SARS, global financial crisis, and social protests without missing a beat |
Estonia | 1992 | Deutsche Mark / EUR | Ended post-Soviet hyperinflation; anchored transition to market economy; joined Eurozone 2011 |
Lithuania | 1994 | USD / EUR | Monetary stability through transition; joined Eurozone 2015 |
Bulgaria | 1997 | Deutsche Mark / EUR | Ended 242%/month hyperinflation; GDP growth resumed; still operating today |
Bosnia-Herzegovina | 1997 | Deutsche Mark / EUR | Post-war monetary stability under the Dayton Accords; unified currency for a divided country |
Why Currency Boards Are Speculation-Proof
The most common objection to currency boards is that speculators can attack the peg. The historical record refutes this entirely — but the theoretical reason is equally compelling:
- A speculator attacks a peg by selling domestic currency, forcing the monetary authority to buy it with foreign reserves
- This works against central banks because central banks can run out of foreign reserves
- A currency board holds 100% foreign reserves against the entire monetary base
- As speculators sell and the board buys, the monetary base automatically contracts
- Contraction raises domestic interest rates, making the attack increasingly expensive
- The peg becomes self-reinforcing: harder to attack the more it is attacked
The Result: No successful speculative attack has ever occurred against a properly functioning orthodox currency board. The Asian Financial Crisis of 1997–98 — which devastated central bank pegs across Southeast Asia — left Hong Kong's currency board untouched.
Comparison: Currency Boards vs. Central Banks in Crisis
Country | Monetary System | 1997–98 Asian Crisis Outcome |
Hong Kong (currency board) | Orthodox currency board (USD anchor) | Currency stable; peg held; no devaluation |
Thailand (central bank) | Managed central bank peg | Baht devalued 55%; IMF bailout |
Indonesia (central bank) | Central bank | Rupiah fell 85%; severe recession; political crisis |
South Korea (central bank) | Central bank | Won devalued 50%; IMF bailout; deep recession |
Malaysia (central bank) | Central bank | Ringgit devalued; capital controls imposed |
The pattern is unambiguous. Currency boards held. Central bank pegs collapsed.
The Hanke-Schuler Research Program
The empirical case for currency boards rests on Hanke and Schuler's systematic historical analysis. Their research program at Johns Hopkins University, co-founded with Sir Alan Walters (Margaret Thatcher's personal economic adviser), examined:
- Balance sheet data for all 70 currency boards
- Inflation performance relative to contemporaneous central bank countries
- Exchange rate stability and real competitiveness outcomes
- Episodes of speculative pressure and their resolution
- Transition dynamics when currency boards were adopted in crisis conditions
The research culminated in Currency Boards for Developing Countries: A Handbook (with Schuler, 1994; 2nd ed. 2015), the definitive reference work on currency board design and implementation.
Related Pages
- The Case Against Central Banks
- Hong Kong — The Original Template
- Indonesia — The Crisis of 1998
- Russia — Blueprint for Reform
- Home: Currency Boards — Return to the Currency Boards overview
Related Topics
- Monetarism — The theoretical foundation
- Hyperinflation — What happens without monetary discipline